 based on over
Financing new windows and doors: What are your options?
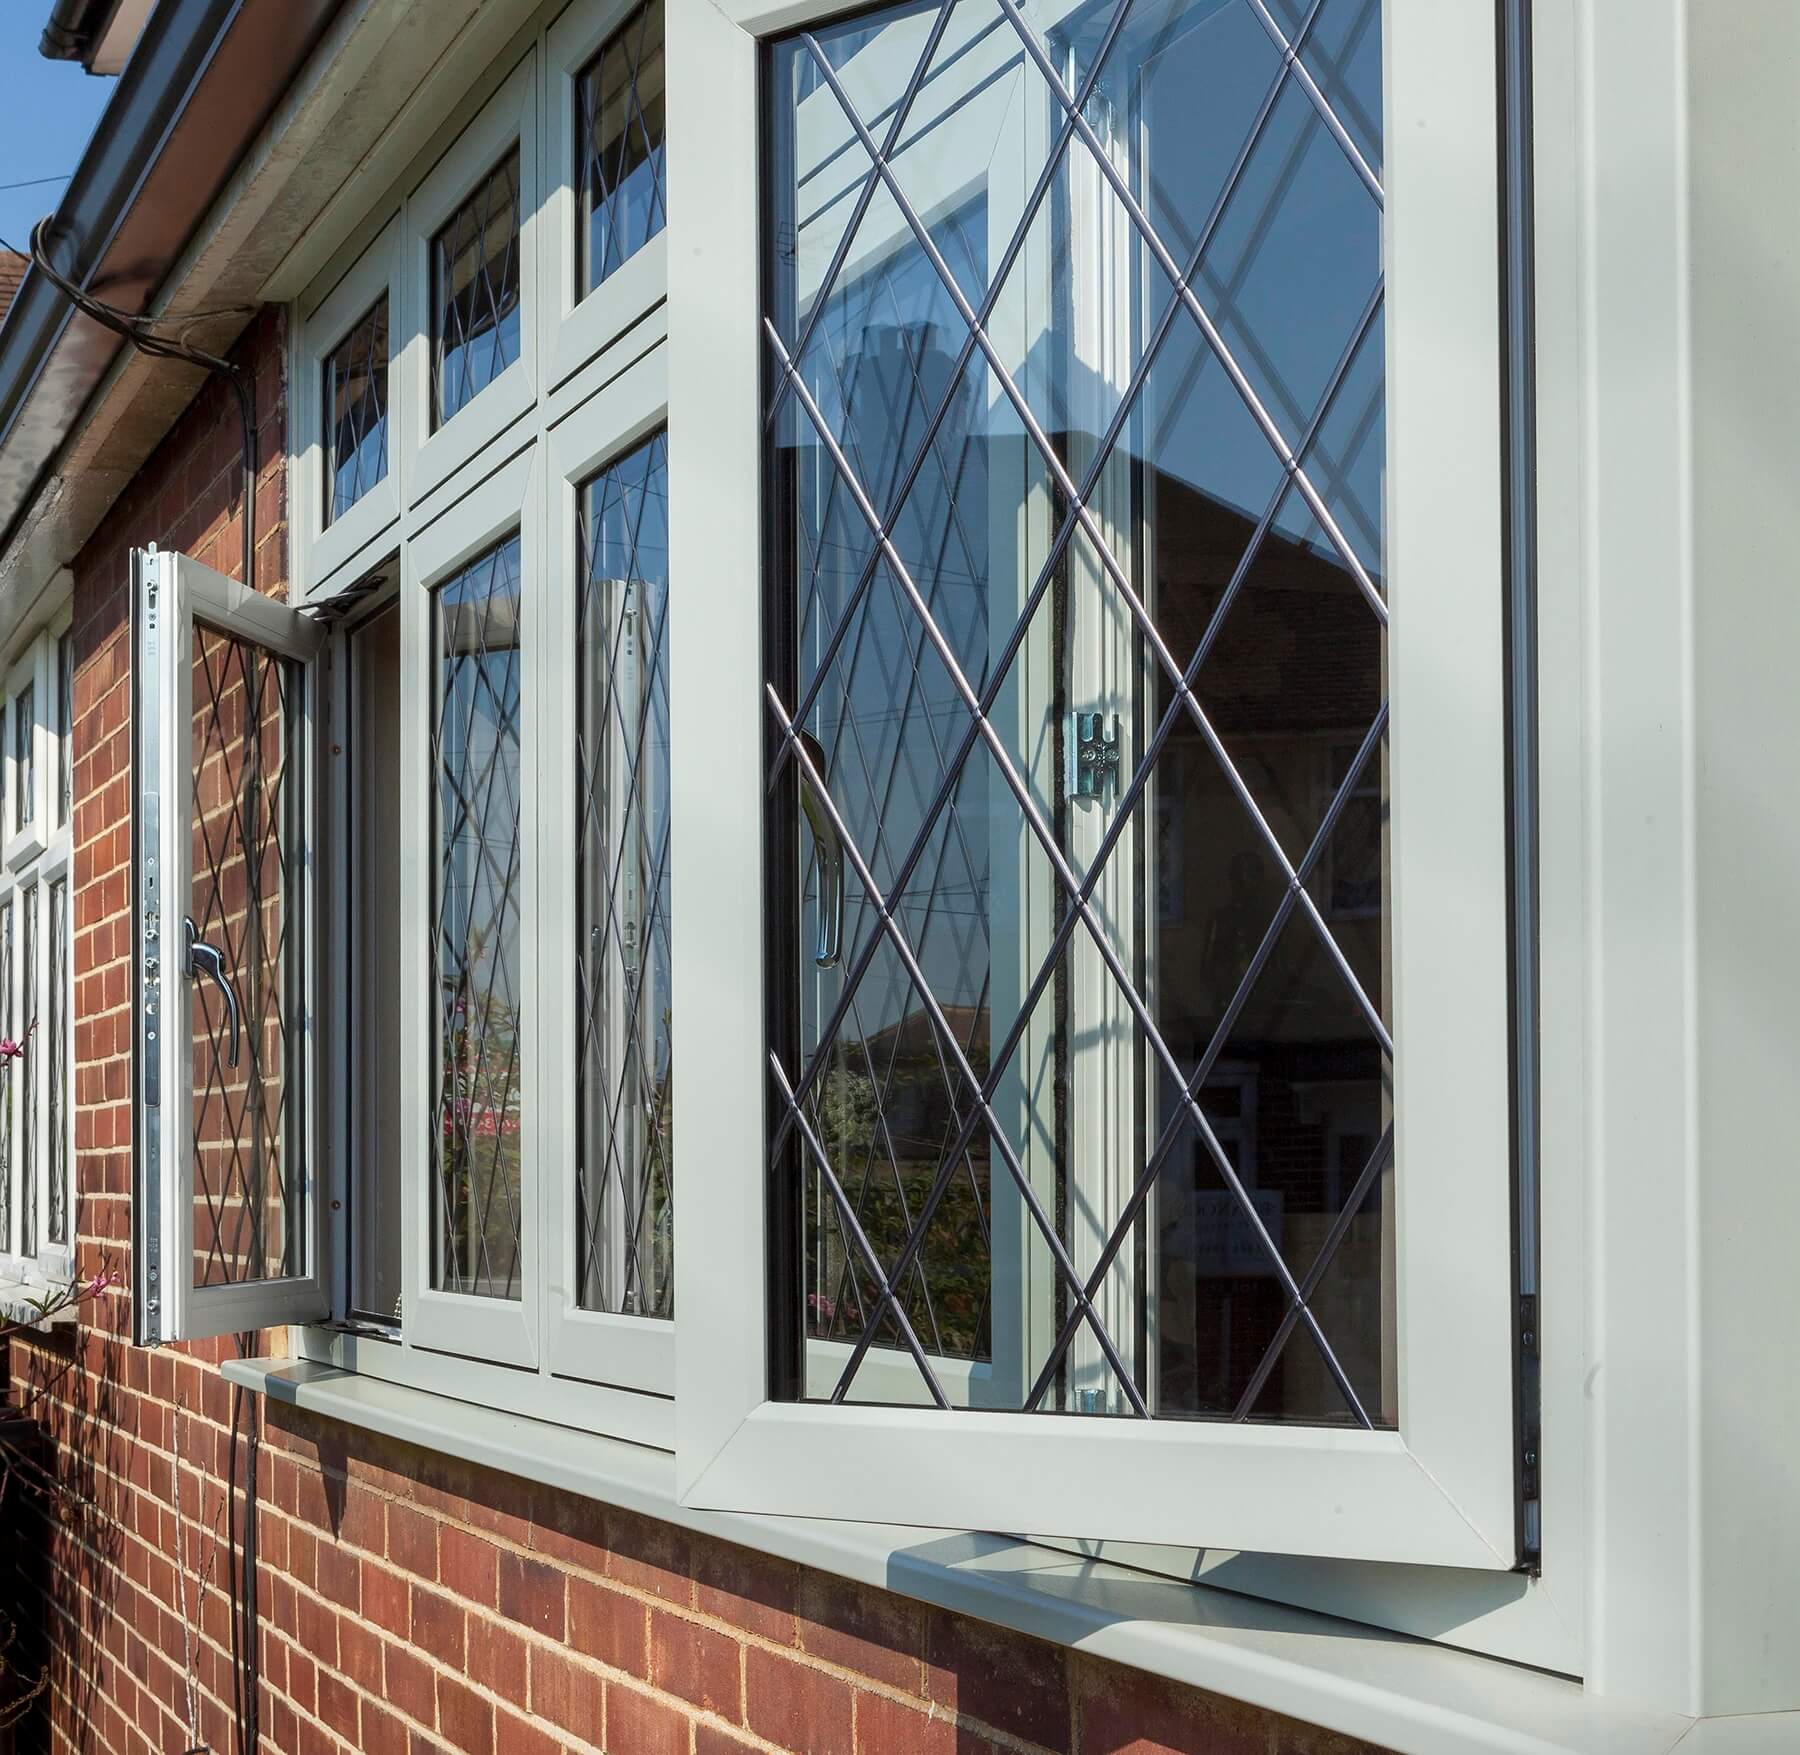
Replacing your windows and doors can improve your home’s comfort, security and energy efficiency. However, the upfront cost can be a concern, particularly if you’re planning a larger home improvement project.
Windows and doors finance can help make these improvements more accessible by spreading the cost over an agreed period. At Albany Windows, we offer four finance options, including 12- and 24-month interest-free credit, Buy Now Pay Later and 10-year rate flexible finance. Each has different repayment terms and spending limits, so it’s important to understand what’s available before choosing a plan.
Whether you’re replacing a single front door or upgrading several windows, understanding your payment options can help you decide what’s affordable.
What windows and doors finance options are available?
Our finance options give you different ways to spread the cost of replacement windows and doors. The right choice depends on your project budget and the repayments you can comfortably afford.
| Finance option | What it offers | What to consider |
| 24-month interest-free credit | Eligible purchases up to £2,500 at 0% APR. | Check that your project falls within the spending limit. |
| 12-month interest-free credit | Eligible purchases up to £5,000 at 0% APR. | Consider whether you can comfortably repay the balance within 12 months. |
| Buy Now Pay Later | Six-month payment deferral before repayments begin. | APRs range from 14.9% to 19.9%, depending on the agreement. Check the deposit, interest rate and total amount repayable. |
| 10-year rate flexible finance | Eligible purchases up to £50,000 over 120 months. | The representative APR is 10.9% fixed. Compare the total interest and amount repayable over the full term. |
The interest-free options have specific spending limits, so a larger installation may not qualify for 0% finance in full. Buy Now Pay Later and 10-year rate flexible finance provide alternatives for larger projects, although interest applies.
The options available depend on your purchase, the finance agreement and the lender’s approval. Always check the APR, deposit requirements and total amount repayable before committing. A longer repayment period may reduce monthly payments but increase the overall cost of borrowing.
Repayments typically start one month after installation, although you should check the terms of your specific agreement.

Finance packages available from Albany Windows
At Albany Windows, we offer four finance options to help homeowners spread the cost of replacement windows and doors.
24-month interest-free credit
For eligible purchases up to £2,500, this option allows you to spread the cost over two years at 0% APR, subject to the agreement.
Our representative example uses a £1,200 composite door purchase with no deposit, repaid through 24 monthly payments of £50. The total amount repayable is £1,200.
12-month interest-free credit
For eligible purchases up to £5,000, this option allows you to spread the cost over one year at 0% APR.
Our representative example uses a £4,800 purchase of flush-look colour woodgrain PVCu windows with no deposit. This is repaid through 12 monthly payments of £400, with a total amount repayable of £4,800.
Buy Now Pay Later
This option provides an initial six-month deferral period, followed by monthly repayments. APRs are available from 14.9% to 19.9%, depending on the agreement.
Our representative example uses a £20,000 solid conservatory roof installation, with a 25% deposit of £5,000. The remaining £15,000 is financed over 66 months, including the six-month deferral period. After this, the agreement involves 60 monthly payments of £387.28 at a representative APR of 16.9% fixed. The total amount payable, including the deposit, is £28,236.80.
The example specifies that no early settlement fee applies during the six-month deferred period. Check your own agreement for the conditions that apply.
10-year rate flexible finance
For eligible purchases up to £50,000, this option allows you to spread the cost over a longer period. It has a representative APR of 10.9% fixed, with the flexibility to make early repayments without penalty.
Our representative example uses a £28,000 conservatory purchase with no deposit. This involves 120 monthly payments of £377.72, with a total amount payable of £45,326.40, including £17,326.40 in credit charges.
Compare the APR, monthly repayments, deposit requirements and total amount repayable before choosing a package. All finance is subject to status and the lender’s terms and conditions.
Is financing new windows and doors worth it?
Whether finance represents good value depends on the agreement and your financial circumstances. Interest-free credit can help spread the cost without paying interest when the agreement’s conditions are met. However, the spending limits mean it may not cover a larger installation in full.
Interest-bearing finance can make bigger projects more manageable through lower monthly repayments, although you’ll need to consider the total amount repayable. Paying upfront avoids borrowing costs but uses savings you may need elsewhere. Choose an option that fits your budget rather than focusing on the monthly payment alone.
Benefits of home improvement finance
Home improvement finance can offer several advantages when you’re planning to replace your windows and doors.
- Spread the cost: Regular repayments can make a larger purchase easier to manage than paying upfront.
- Keep savings available: Finance may allow you to retain money for emergencies and other household expenses.
- Plan your budget: A set repayment schedule helps you account for the cost alongside your regular bills.
Make sure you can afford the repayments and understand the full cost of borrowing before proceeding.
What are the alternatives to windows and doors finance?
Finance isn’t the only way to pay for new windows and doors. Depending on your circumstances, you may prefer to use savings or explore other forms of borrowing.
Paying from savings
Using savings avoids taking out credit or paying interest. However, retain enough money for emergencies and essential expenses before funding home improvements.
Taking out a personal loan
A personal loan or home improvement loan may allow you to borrow the amount needed and repay it over an agreed period. Compare the APR, repayment terms and total cost with Albany’s finance options.
Using a credit card
A credit card may suit some purchases, depending on your available credit and interest rate. Some cards offer introductory interest-free periods, but check when these end and what you’ll pay if you haven’t cleared the balance.
Borrowing against your home
A further advance on your mortgage or remortgaging may provide another way to fund a larger project. However, borrowing secured against your property means your home could be at risk if you fail to keep up with repayments. Consider the costs and risks carefully.
What should you check before applying for finance?
Before choosing a finance plan, make sure you understand the agreement and can comfortably afford the repayments.
- Monthly repayments: Will the payments fit your budget alongside household bills?
- APR and interest rate: Is the agreement interest-free, or will interest apply? Is the rate fixed?
- Total amount repayable: How much will you pay over the full term, including interest and applicable charges?
- Amount of credit: Does your purchase fall within the plan’s spending limit?
- Deposit requirements: Will you need to pay a deposit, and how will it affect the amount borrowed?
- Credit eligibility: Will the lender carry out a credit check, and what criteria apply?
- Early repayment: Can you settle the balance early, and are any charges involved?
- Missed payments: What happens if you cannot pay on time?
Request a quotation before applying and read the agreement carefully. Finance is subject to application, status and the lender’s approval.
Frequently asked questions
Can I get finance for replacement windows and doors?
Yes, we offer four finance options to help spread the cost. These include 24-month interest-free credit for eligible purchases up to £2,500, 12-month interest-free credit up to £5,000, Buy Now Pay Later and 10-year rate flexible finance for purchases up to £50,000. Availability depends on the agreement and lender approval.
Will I need to pay a deposit?
Deposit requirements depend on the finance option and agreement. Our published examples for the 12- and 24-month interest-free plans and 10-year flexible finance use no deposit. The Buy Now Pay Later example uses a 25% deposit. Your own requirements may differ, so confirm the details before applying.
Will applying for finance affect my credit score?
Applying for finance may involve a credit check, which the lender will use to assess your application. The type of check and its potential effect on your credit file depend on the lender.
Can I repay my finance early?
Early repayment conditions vary between agreements. Our 10-year rate flexible finance option allows early repayments without penalty, reducing the interest paid. The Buy Now Pay Later example specifies no early settlement fee during its six-month deferred period. Check your agreement for the conditions that apply.
Explore your finance options with Albany Windows
The upfront cost of replacing your windows and doors doesn’t have to be the only factor in your decision. Understanding the finance options available can help you plan your project and decide what fits your budget.
At Albany Windows, we offer four finance options, including 12- and 24-month interest-free credit, Buy Now Pay Later and 10-year rate flexible finance. With different spending limits, APRs and repayment periods, our team can help you understand the options available for your project.
Call us on 01242 511384 or email sales@albanywindows.co.uk to discuss your requirements and request a free, no-obligation quote. You can also explore our windows, doors and finance options.
Albany Windows Ltd is authorised and regulated by the Financial Conduct Authority (FRN 737577). We are a credit broker, not a lender, and offer credit facilities from a panel of lenders. Finance is subject to status and the lender’s terms and conditions.